Why New Construction Looks Better at 7% (Builder Rate Buydowns Explained)
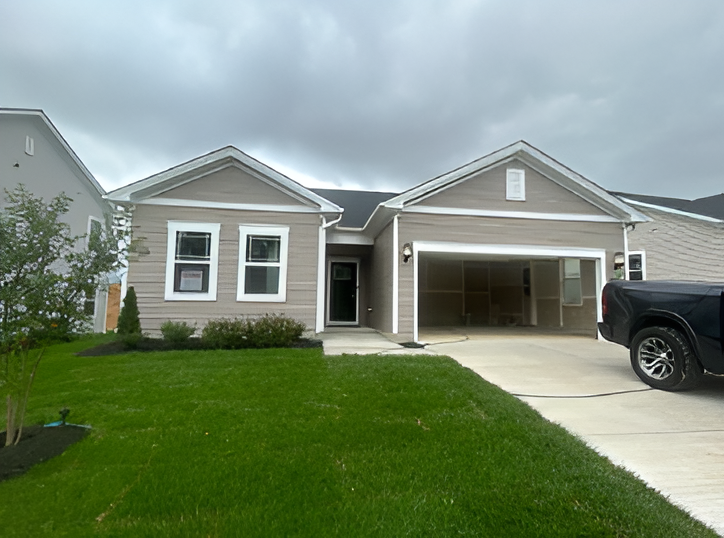
With rates up near 7%, new construction has quietly become one of the few ways to get a meaningfully lower rate, through builder-paid permanent buydowns you can't replicate on a resale home. Here's the catch.
30 year fixed rates jumped from around 6% to nearly 7% recently, and it changed the math on something many buyers in the DMV overlook: new construction.
Why builders can do something resale sellers can't
When rates rise, builders have a problem a regular seller doesn't. They have standing inventory, finished or nearly finished homes they need to sell before the next fiscal quarter, and they can't just wait for the market to warm up. So instead of cutting the price (which hurts the value of every other home in the community), they buy down the rate.
A builder-paid permanent rate buydown is the thing that's hard to replicate anywhere else right now. The builder pays points up front to permanently lower your interest rate for the life of the loan, often well below what you'd get on a resale home. On a 30-year mortgage, even a point of rate difference is a large monthly number, and over the life of the loan it's enormous.
A regular seller usually can't match this. An individual selling a resale home might offer a closing-cost credit, and that credit can be used toward a buydown, but it's typically a fraction of what a national builder will spend to move standing inventory. Builders have the margin, the volume, and the fiscal-calendar pressure to buy rates down aggressively in a way an individual seller simply doesn't. That's the structural advantage, and it only shows up when rates are high enough that buyers need the help.
The catch: you usually have to use the builder's lender
In most cases, the big buydown incentives are tied to using the builder's in-house or preferred lender. The builder isn't buying down your rate out of generosity, they're doing it to close the home, and they want the loan to run through their own lender to control the process and capture the business.
That creates a real decision. The builder's lender gets you the buydown, but you should still:
- Compare the builder-lender's full costs, not just the rate. A great rate with inflated fees can erase the benefit.
- Get a competing quote from your own lender so you know what you're giving up or gaining.
- Read what happens if you don't use their lender. Sometimes the home price itself goes up, sometimes you just lose the rate incentive.
The honest way to evaluate it: get the builder-lender's full loan estimate, get an independent lender's loan estimate on the same home, and compare the all-in monthly payment and total cost. Often the builder buydown wins on a high-rate day. Sometimes it doesn't once the fees are in. You won't know until you run both.
What this means for a buyer right now
If you're shopping in this market and rates are scaring you off, new construction deserves a second look specifically because of the buydown math. A resale home at a slightly lower price can still cost you more per month than a new build with a builder-paid permanent buydown, because the rate does more to the payment than a modest price difference does.
It isn't automatic, and it isn't right for everyone. New construction has its own tradeoffs: location (new communities are often farther out), timelines, and the builder-lender question above. Also, importantly, different builders offer different incentives. Some may offer temporary rate buydowns for a year or two, while others may offer permanent rate buy downs. Permanent buydown is the more attractive option in my opinion.
If you're weighing a new build against a resale home and want someone to run the actual payment both ways, including whether the builder buydown holds up once the fees are in, that's exactly the kind of comparison I do before my clients commit.